All practical guides
Downsizing to Norfolk: stamp duty, equity release and where it actually works
The practical version: SDLT replacement-of-main-residence rules, the honest Equity Release Council trade-off, July 2026 UK HPI prices by district, five Norfolk towns where downsizing actually works and what the removal and GP registration side looks like.
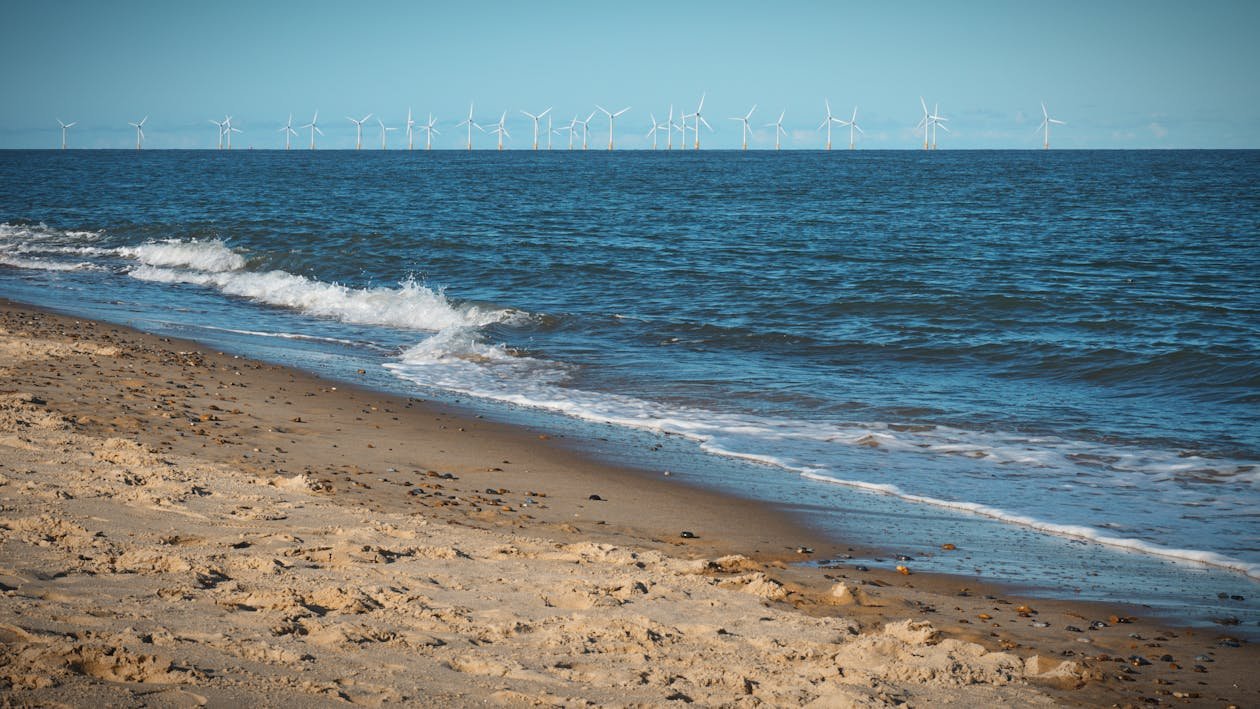
Downsizing to Norfolk sounds like the easy half of the move. Sell the four-bedroom detached in the south, buy a two-bedroom near the sea, bank the difference. In practice the arithmetic is only part of it. The stamp duty rules bite in an awkward place when the sale and the purchase don’t line up, equity release reads simpler than it is, and the shortlist of towns where you can actually walk to a GP with your shopping is shorter than most property-portal filters admit. This is the practical version of the piece, with the numbers sourced and the trade-offs named plainly.
What you actually gain on the sale
The equity gap is the headline figure, and it varies more by district than most downsizers assume. The UK HPI for July 2026 reports the following average sold prices across the seven Norfolk local authority districts. These are HM Land Registry figures, published monthly, and they lag the point of sale by about four months.
| District | All dwellings | Detached | Semi | Terrace | Flat / maisonette |
|---|---|---|---|---|---|
| Broadland | £313,407 | £421,798 | £274,748 | £226,397 | £145,444 |
| South Norfolk | £311,587 | £428,324 | £276,178 | £229,757 | £133,971 |
| North Norfolk | £292,563 | £409,147 | £270,482 | £227,561 | £154,534 |
| Breckland | £268,905 | £367,443 | £239,686 | £192,871 | £108,177 |
| King’s Lynn & West Norfolk | £265,715 | £364,968 | £242,469 | £198,571 | £113,307 |
| Norwich | £224,323 | £455,015 | £287,637 | £246,876 | £141,187 |
| Great Yarmouth | £209,114 | £315,604 | £213,496 | £167,632 | £105,307 |
Three things worth noticing. First, Broadland and South Norfolk sit well above the Norfolk average of £269,185; the commuter-belt premium is real and it is where most downsizer-into-Norfolk flows land. Second, the flat averages in those two districts (around £134,000 to £145,000, July 2026) are what makes a downsize actually move the needle on retirement income rather than just change the postcode. Third, North Norfolk is down 3.1% on the year while the East of England as a whole is up 0.5%; the coast has been softening since spring and that affects both what you sell for if you downsize within North Norfolk and what you pay if you buy there.
A worked example. A retiring couple selling at the East of England regional detached average (£524,064, July 2026) and buying a two-bedroom bungalow in Broadland at the semi average (£274,748) releases around £249,000 before costs. If they move inside Norfolk, from a Broadland detached to a Broadland semi, the gap is smaller, around £147,000. The within-Norfolk move still works, but it is a different financial decision from the cross-regional one.
Stamp duty when you replace your main residence
Where downsizers get caught is the gap between the two transactions. If you buy the new place before you have sold the old one, HMRC treats the new purchase as an additional residential property and the standard SDLT rates in England and Northern Ireland rise by five percentage points at every band. For a £275,000 Broadland bungalow bought before the old home is sold, SDLT is £17,500 (5% on the first £125,000, 7% on the next £125,000, 10% on the £25,000 above £250,000) rather than the £3,750 a standard replacement buyer would owe. That is £13,750 of surcharge sitting on the completion statement.
The money comes back if you sell the old main home within three years of buying the new one. HMRC’s guidance on the higher rates is explicit: dispose of the previous main residence within three years, apply for a refund within 12 months of either the sale or the filing date of the SDLT return on the new home, whichever is later. The exceptional-circumstances extension exists (the published example is government restrictions preventing a sale) but is not a general discretion to extend; HMRC takes the three years as hard unless the delay has an identifiable cause outside your control.
If selling first and buying second is manageable, the surcharge never arises and the deposit the equity throws off is yours to put down. Short-term bridging between the two completions is the usual commercial answer, but bridging is expensive at current rates and the number of downsizers who come out ahead on bridging-fees-plus-interest versus parking in rented for three months is smaller than lenders imply. The sequence matters more than the loan product.
Moving to Norfolk this year?
Get the free Norfolk Relocation Pack: all 46 towns we cover on one table, on price, council tax, population, trains and distance to Norwich, plus a week-by-week move checklist. The download appears here as soon as you enter your email.
Unsubscribe any time.
Equity release: the standards and the compounding problem
If the sale and purchase don’t produce enough of a gap to fund the retirement budget, equity release is the next lever the industry recommends. It is tightly regulated and the Equity Release Council’s product standards cover the main consumer risks. A lifetime mortgage carrying the Council’s badge has to meet six standards: the interest rate is fixed, or if variable it carries a fixed cap; you can live in the property for the rest of your life; you can move to a suitable alternative property subject to lender criteria; the no-negative-equity guarantee means you or your estate will never owe more than the property is worth after reasonable sales costs; you can make voluntary repayments without penalty, subject to the provider’s lending criteria; and early repayment charges are waived if you move permanently into long-term care on receipt of a medical practitioner’s certificate.
Those six safeguards address the horror stories from the 1990s. What they do not do is change the compounding arithmetic, which is where equity release goes wrong for most households that use it. A £60,000 release at a fixed 6.5% roll-up rate doubles roughly every eleven years. Twenty years later the debt is around £212,000; thirty years later it is around £398,000. The property has probably not kept pace. The no-negative-equity guarantee stops the shortfall landing on your estate, but it does not stop the shortfall itself, and the shortfall is usually the inheritance.
The honest version: equity release works if you need the money now and the inheritance consequence is understood by whoever would otherwise inherit. It does not work as a way of avoiding the downsizing move, because the compounding costs more than the stamp duty, removals and emotional friction of actually selling and buying. If you can downsize instead and release the equity through a smaller house, you almost always should.
Where in Norfolk a downsize actually works
The property-portal filter for bungalows across Norfolk returns thousands of listings. The filter for “bungalow near a GP, a bus stop and a shop you can walk to” returns far fewer. These five places are the ones where the practical criteria stack up.
Dersingham. West Norfolk, two miles from Sandringham. Bungalow stock is heavy because the village grew in the mid-twentieth century on flat land north of King’s Lynn. The Lynx 34 bus runs to the Queen Elizabeth Hospital in King’s Lynn in about 12 minutes to the hospital stop. Carole Brown Health Centre on Church Lane is the GP; the Central Co-op at 10 Lynn Road covers daily shopping. July 2026 King’s Lynn & West Norfolk semi average £242,469. See our Dersingham guide for the detail.
Diss. Right on the Suffolk border with a train station on the Norwich-to-London main line (Liverpool Street in about 95 minutes, Norwich 20). A proper market town with a GP cluster, a hospital at Harleston for routine outpatient appointments and the usual high-street spread. Not bungalow-dominant, but single-storey stock on the newer estates to the west and north. South Norfolk semi average £276,178 (July 2026).
Wymondham. Mid-Norfolk, nine miles south of Norwich. Train to Norwich 10 minutes, Cambridge 70. The Norfolk and Norwich University Hospital is 25 minutes by car. GPs at Wymondham Medical Centre; Waitrose and Lidl in town. Bungalow stock concentrated on the Silfield and Spooner Row sides. South Norfolk’s annual price change was +1.5% to July 2026, slower than Broadland.
Reepham. North of Norwich on the B1145, no train but good bus links to Norwich (the Sanders Coaches 45). Smaller than the others, but denser than it looks: GP, chemist, two supermarkets, a market square. Bungalow stock is on the Whitwell and Kerdiston approaches. North Norfolk softening prices (-3.1% annual to July 2026) make this a buyer’s year.
Hunstanton. The only west-facing resort on the east coast of England, which is the tourist-board way of saying you watch the sun set over the sea rather than rise out of it. Flat ground, lots of bungalows, a hospital at King’s Lynn 20 minutes away. The downside is that it is at the end of the A149 and winter services thin out considerably; this is a town that works in high summer and in June and September more than in January.
Towns that look obvious on paper but have specific caveats: Cromer (the coast is beautiful but hospital access is Norfolk and Norwich, not local, and the hills in and out of town are harder than they look on foot); Sheringham (same hospital issue, same hills); Burnham Market (lovely but the median price makes a downsize into it hard to engineer unless you are coming from London); Caister (bungalow stock is there but the coastal-erosion planning overlay affects a strip of the seafront and should be checked parcel by parcel before offering).
Removal costs: Norfolk ranges
Local-move quotes from Norfolk firms land roughly where you would expect. Britannia Alan Cook quotes £500 to £1,000 for a one- or two-bedroom local move within Norfolk and £1,000 to £2,000 for a three- or four-bedroom move. Long-distance moves out of or into Norfolk at the three- to four-bedroom size tend to come in at £1,500 to £2,500 with that firm, and up to £3,500 if the origin or destination has access problems or the move falls on a weekend. BizHub365’s directory of Norwich firms gives £1,500 to £2,400 for a three-bedroom move. These are approximate; a quote from two or three firms on your actual property will tighten the figure quickly.
Three practical savings. Pack yourself and pay the firm for the lift only; this cuts about 20% off most quotes but you need to start six weeks early if the house is full of thirty years of accumulated things. Move midweek, not Friday. Friday is the premium day because it is the day most completions fall. If the downsize is to a smaller place, dispose before you pack: a Norfolk charity-shop run is cheaper and faster than paying the removal firm to carry things you will throw away six months later anyway.
GP registration and the services that come with it
GP registration in England is simpler than most new arrivals assume. The NHS guidance is unambiguous: you need to give the surgery your name, date of birth and address; you do not need ID, proof of address or proof of immigration status. Most Norfolk practices accept online registration through the NHS website or the NHS App; a paper form or the surgery reception works too. You should be told you are registered within about five days, though it can take longer.
Where it gets practical is that surgeries can refuse. The usual grounds are that the practice is not accepting new patients, that you live outside its catchment, or that you have been removed from the list in the past. A refusal has to come in writing within 14 days with the reason. If the practice you want is full, phone round the two or three next nearest; list openings move month to month and a wait of six weeks is not unusual in parts of west and north Norfolk where the retired population has been growing faster than the GP workforce.
Choosing a surgery outside your area is allowed under national rules dating from January 2015, but comes with caveats: home visits, out-of-hours cover and community services (physiotherapy, district nursing) may not be available in the same way as a local registration. If you expect to need those services, register with a local practice even if a slightly further one looks more attractive on the website.
Dentistry is a harder picture, in Norfolk and most other English counties. NHS dental availability for new adult patients is thin; a June 2026 parliamentary answer put the number of Norfolk and Waveney practices accepting new NHS adult patients at nine. If dental is important to you, phone around before completion rather than after.
Frequently asked
If I buy before I sell, how long do I have to sell the old home to get the SDLT surcharge back?
Three years from the completion date of the new purchase. The refund claim then has to be filed within 12 months of either the sale of the old home or the filing date of the SDLT return on the new one, whichever is later. HMRC publishes an online form for the refund; a conveyancer will usually file it on your behalf.
Do I need to be moving into Norfolk, or does this apply to downsizers already here?
The SDLT replacement-of-main-residence rules apply the same whether you are moving into Norfolk from outside or moving house within Norfolk. The equity gap, however, is smaller for within-Norfolk moves; the within-Broadland worked example above (detached to semi, roughly £147,000) is typical.
Is a bungalow always better than a flat for retirement?
No. Bungalows have no stairs, which is the usual argument, but they also have gardens and heating-and-maintenance costs that scale with square footage. A ground-floor flat in a well-run block often beats a bungalow for a single-person household who does not want a garden; the service charge replaces the maintenance budget rather than adding to it. The right answer varies by household, and the honest version is that most people get this wrong in their first downsize and get it right in their second.
What council tax should I expect?
Norfolk council tax bills come in three layers: the county council, your district council, and the parish or town precept (plus the police and the fire service). The practical check is to look up your prospective address on the gov.uk council tax finder, which returns the full Band D figure including precepts for your actual parish. Band D is the standard reference point even though many smaller bungalows sit in Band A, B or C and attract a reduced percentage of the Band D rate.
Related: Retiring to Norfolk: towns, hospitals and getting about, Best places to retire in Norfolk: eight to shortlist, Cost of selling a house in Norfolk, Cost of buying a house in Norfolk.
By Sarah Ellis, coast and lifestyle editor. Sources: UK HPI July 2026 release (HM Land Registry); HMRC SDLT guidance on buying an additional residential property; Equity Release Council product standards; NHS guidance on registering with a GP surgery; Britannia Alan Cook published quote ranges; BizHub365 Norwich removals directory. Figures and policy wording were checked against primary sources on the day of publication. Numbers move; policy moves; if you are planning a transaction, verify at the source before signing.
Planning a move to Norfolk?
Our guides to hiring the firms a move needs.
We earn no commission on these links. Paid placements are sold separately and always labelled. See our advertising and disclosure page.